Retail investors get one number before an IPO opens, which is the price band, and it tells them nothing about whether anyone credible thinks it is fair. The anchor book does.
An anchor investor is a qualified institutional buyer allotted shares one working day before the public issue opens, at a price inside the announced band, with a minimum application of Rs 10 crore. The list of who bid and for how much is published before retail bidding starts, which makes it the only piece of genuine institutional price validation a retail applicant gets to see in advance.
Most people glance at the total and move on. The total is the least useful part.
How the anchor book is built
The mechanics decide what the signal is worth. Up to 60% of the qualified institutional buyer portion may be allocated to anchors, and since the QIB portion is usually 50% of the net offer, the anchor book can absorb about 30% of the entire issue.
There is a deliberate domestic tilt inside it. One third of the anchor portion is reserved for domestic mutual funds, and a 6.67% slice for insurers and pension funds was added with effect from 30 November 2025, with any undersubscription in that carve-out reallocated to mutual funds.
The three questions the book actually answers
The first is whether institutions accepted the price. Anchors bid within the band, and a book filled at the top of the band is a different statement from one that needed the floor. This is the only pre-listing evidence of professional demand at the exact price retail is being asked to pay, which is why it matters more than the grey market premium our GMP explainer describes, since GMP is an unofficial quote and the anchor book is a filing.
The second is who showed up. Domestic mutual funds, insurers and long-only global funds hold positions for years, while some multi-strategy and hedge fund names are structurally shorter term. A book weighted towards domestic mutual funds is a slower-moving shareholder base than one weighted towards fast money, and the difference shows up in how the stock trades in month two, not week one.
The third is concentration. Twenty names taking modest slices is a broader endorsement than three names taking most of the book, because concentrated anchor holdings become concentrated selling pressure at the same moment.
The expiry date on the signal
This is the part retail applicants consistently miss. Fifty per cent of anchor shares unlock after 30 days and the rest after 90 days from allotment, a two-stage structure introduced in April 2022 precisely because a single 30-day lock-in created a supply cliff.
A calendar of anchor unlock dates is therefore a calendar of potential supply, and it sits alongside the larger pre-IPO shareholder lock-ins our IPO lock-in expiry piece tracks. Anchors are not obliged to sell, and good ones often do not. The point is that the option arrives on a known date.
Reading a live one
The immediate test is the National Stock Exchange issue. Anchor bidding is on 16 September 2026, the public issue runs from 17 to 21 September at a band of Rs 1,700 to Rs 1,785 per share, and the issue is a Rs 22,562 crore pure offer for sale. Our NSE IPO analysis covers the FY26 profit decline that anchors are pricing against.
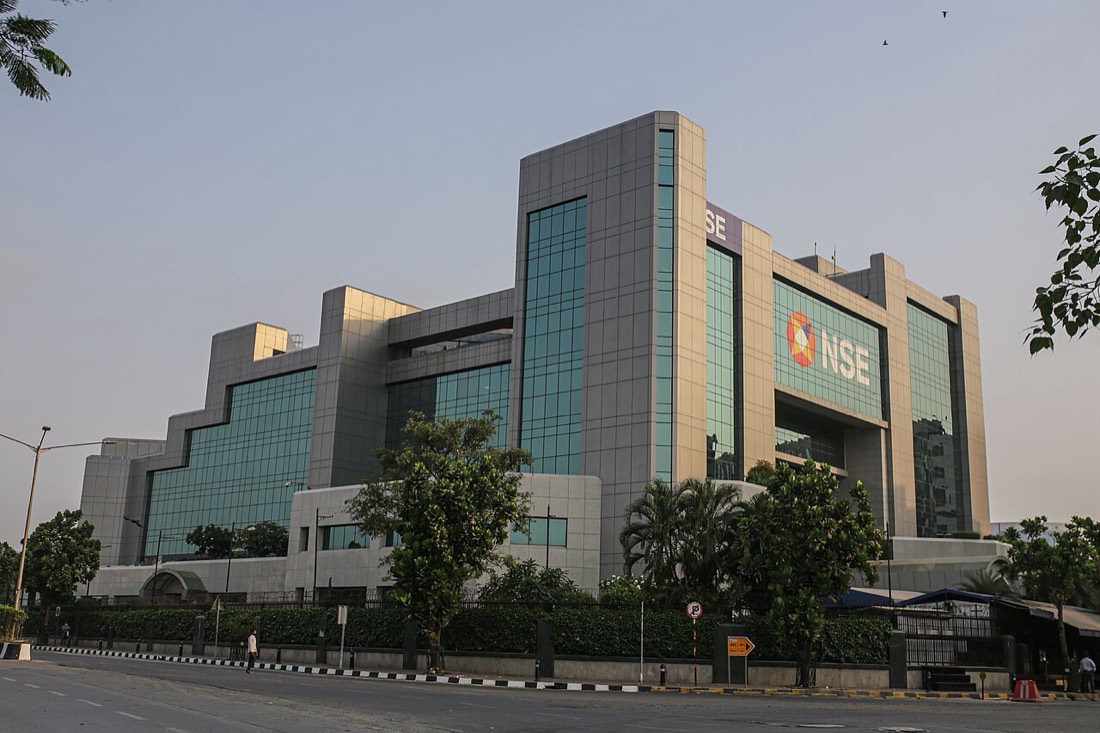
The book was filed on 16 September: Rs 6,746.18 crore from 189 anchor investors, all at the Rs 1,785 top of the band, for 3,77,93,739 shares. Domestic depth was real, with 98 mutual fund schemes and 27 life insurers including LIC and the SBI group, while the foreign side read like a list of the world's most patient money: the Monetary Authority of Singapore, GIC, the Abu Dhabi Investment Authority, Norges Bank, Goldman Sachs and Fidelity. That is a long-only, sovereign-heavy book, which is the kind that tends not to rush for the exit on day 30.
A large anchor book in a large issue proves institutions were willing to fund it, not that the price is right, and the difference between those two sentences is most of what separates a disciplined IPO applicant from a hopeful one. The same discipline applies to the mechanics of applying, which our how to apply for an IPO guide covers, and to reading institutional flows generally, in how to read FII and DII activity.
The anchor book is the closest thing the Indian primary market gives you to watching professionals show their hand before you play yours. It is worth more than an hour of your attention, and almost nobody spends ten minutes on it.