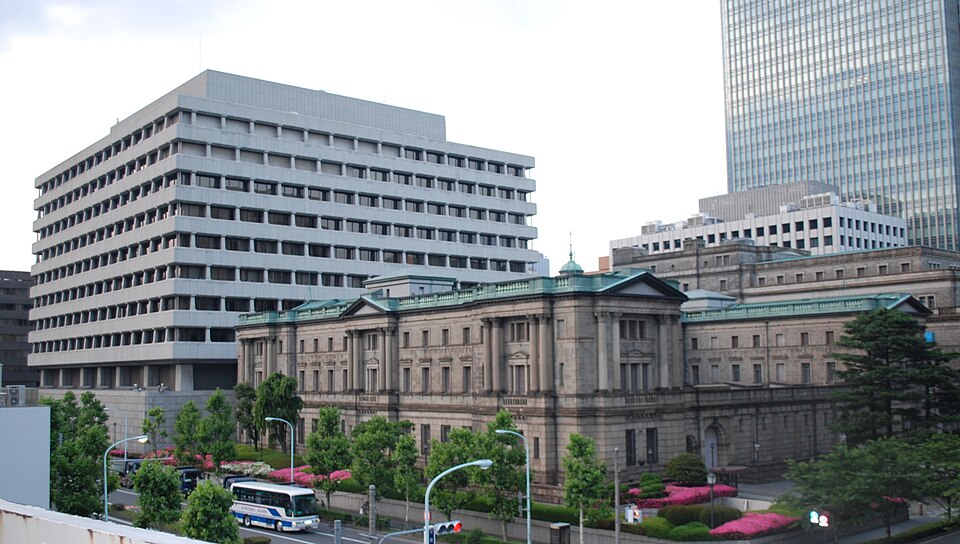
The textbook says a central bank raising interest rates should attract capital and lift its currency. On 18 September 2026 the Bank of Japan raised rates and the yen fell. Both things can be true, and the gap between them is one of the most useful ideas in markets.
The BOJ lifted its policy rate by 25 basis points to 1.25%, the highest since 1995, in a 7 to 2 vote. The dollar then rose about 1.2% against the yen to a two-week high near 157.84.
What the textbook actually says
The mechanism is real. Higher domestic rates raise the return on assets denominated in that currency, which attracts capital, which raises demand for the currency. Economists call the formal version interest rate parity, and over long periods it broadly holds.
The part that gets skipped is timing. Markets price expected policy, so by the time a widely anticipated decision arrives, the currency has usually already moved. What remains to be traded on the day is the difference between what was expected and what was delivered, including the tone.
Why this hike disappointed
Three details did the work, and none of them was the rate itself.
A hike passed with two dissents tells you the committee may struggle to deliver the next one, and a currency trades the next one. That is why the yen weakened into a tightening decision, and why Japanese equities rallied at the same time.
Currencies trade the path, not the print.
The same idea, read from India
The rupee is a cleaner example than most because both sides of its rate gap have been moving. The Reserve Bank of India has held the repo rate at 5.25%, but the rupee still breached 96 per dollar in September 2026, because the Federal Reserve raised rates to 3.75% to 4.00% on 16 September and US yields reached their highest since 2007.
Nothing the RBI did explains that move, and nothing the RBI could have done on the day would have reversed it, which is the practical limit of domestic policy against a global rate cycle. Our rupee versus dollar page tracks the level and our 10-year at 5% piece covers the yield side.
When the textbook does hold
Over longer horizons the relationship reasserts itself. A country that keeps rates persistently higher than its trading partners, with stable inflation and open capital flows, tends to see its currency supported, which is why the dollar has strengthened through a tightening cycle rather than weakened.
The exceptions are informative. A rate rise driven by an inflation problem the central bank is struggling to control can weaken a currency, because investors read it as a symptom rather than a signal of strength. The same 25 basis points can mean confidence in one country and distress in another, and the bond market usually tells you which by whether long yields fall or rise alongside the hike.
How to read the next decision
Check what was priced before the meeting. Futures-implied probabilities, forward rates and bond yields tell you what the market already believed. Above roughly 80% priced, the decision is not the event.
Read the vote split before the statement. It is the least spun number in the release.
Then read the guidance for what it removes rather than what it adds. A central bank that stops describing future moves has told you something, even when the words sound neutral, and Chair Kevin Warsh removing forward guidance from FOMC statements is the same practice in a different institution.
And treat any single currency move as noisy. Rate differentials explain direction over quarters. Over days, positioning, liquidity and one cautious sentence in a press conference can dominate, which is exactly what happened to the yen this week.
The useful takeaway is not that the textbook is wrong. It is that the textbook describes where a currency settles, and markets spend most of their time trading the distance between here and there.